Top 6 Lenders for Plastic Surgery Loans for Bad Credit in 2026
Last updated: 2026-11-08
Navigating the financial side of cosmetic procedures can feel like walking through a minefield. Many patients want to prioritize their appearance but find themselves staring at a daunting price tag that doesn’t align with their current bank balance. This is especially true when a credit score isn’t quite where you want it to be. Whether you are looking at a non-invasive neurotoxin treatment, a series of dermatological procedures, or a major surgical transformation, the cost often extends beyond the surgeon’s fee to include anesthesia, facility fees, and post-operative recovery supplies.
Finding a lender that understands your situation is vital. You need to balance the urgency of your procedure with the long-term reality of monthly repayments. A decision made in the excitement of a consultation can lead to years of financial strain if the terms are poorly understood. This guide looks at various lenders to help you decide which path offers the most stability for your unique financial health.
- CareCredit
- Elite Personal Finance
- FastLendGo
- United
- Ualett
- Quick Credit
Evaluating Financing Options for Cosmetic Procedures
To create this list, several key factors were examined. The primary focus was on how accessible these loans are for individuals who do not possess a pristine credit history. We looked at whether lenders provide quick decisions, which is crucial when scheduling a surgeon’s time. In the medical field, many top-tier clinics have limited availability; missing a surgical window because of a week-long loan approval process can be frustrating and can even impact your recovery timeline.
Furthermore, the flexibility of the repayment terms played a massive role in the ranking. A lender might offer a high loan amount, but if the interest rates are predatory, the procedure becomes a lifelong debt burden. We prioritized transparency and the ability to prequalify without damaging your score. We also considered the «cost of capital»—not just the interest rate, but the total amount you will have paid back by the end of the loan term. A lower monthly payment often comes with a much longer term, which can significantly increase the total interest paid.
| Lender Name | Max Loan Amount | Credit Requirements | Speed of Funding |
|---|---|---|---|
| CareCredit | see site | Subject to approval | Instant decisions |
| Elite Personal Finance | $5,000 | 400 to 500 | 5 minutes |
| FastLendGo | $5,000 | Bad/Fair/Good | Quick access |
| United | see site | see site | see site |
| Ualett | see site | Gig worker focused | Fast funding |
| Quick Credit | $3,000 | Bad credit friendly | Minutes |
Ranking the Best Financing Options
1. CareCredit
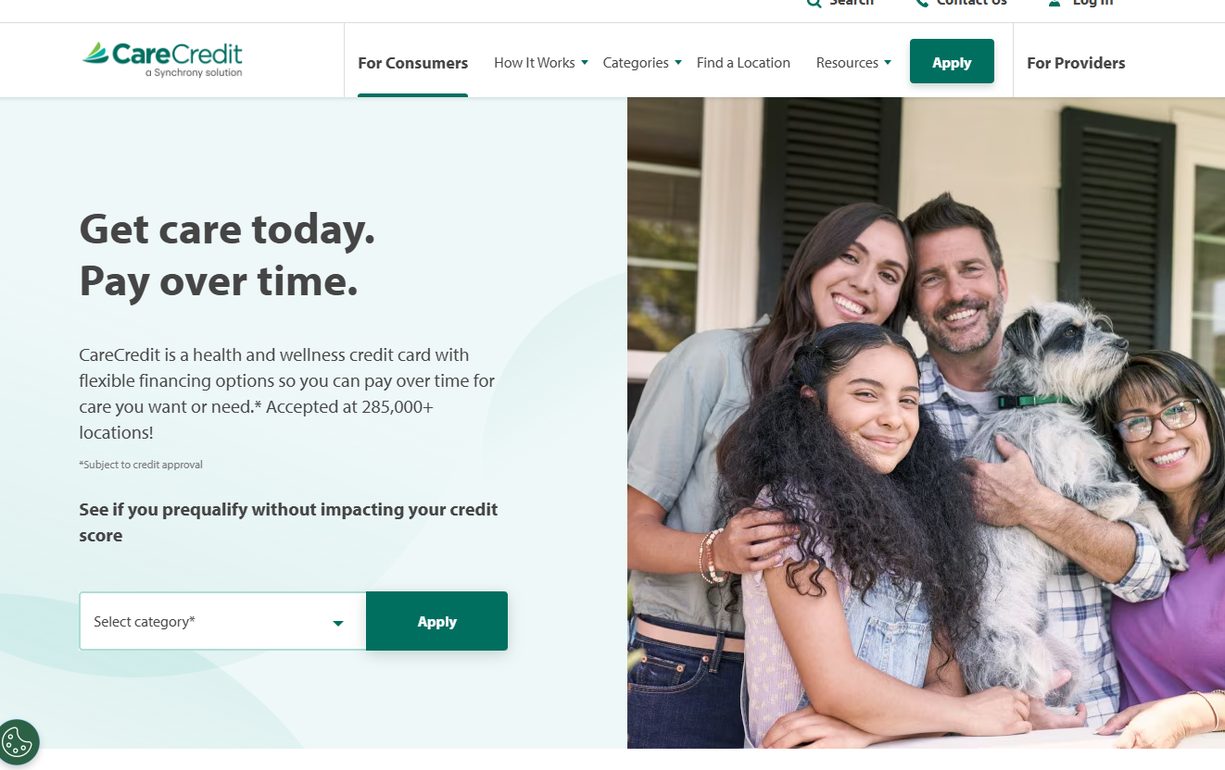
This health and wellness credit card is a titan in the medical financing world. It is widely accepted at over 285,000 locations, making it a highly versatile tool for various aesthetic needs. From dental implants to elective plastic surgery, the ubiquity of CareCredit makes it a standard in the industry. The ability to pay over time is a significant draw for many patients.
For those looking to spread out the cost, CareCredit offers promotional financing options for purchases of $200 or more. These promotions often take the form of «no interest if paid in full within 6, 12, or 18 months.» This is a powerful tool, but it is a double-edged sword. If you fail to pay the balance in full by the end of the promotional period, many lenders charge the interest retroactively from the original purchase date. This can result in a massive, unexpected charge that can derail your budget.
Pros:
- Massive network of accepted locations.
- Instant credit decisions upon application.
- Promotional financing for purchases over $200.
Cons:
- Subject to credit approval.
- Requires a credit card structure which may carry high interest if promotional periods lapse.
2. Elite Personal Finance
Elite Personal Finance caters specifically to those who might be turned away by traditional banks. They offer personal loans for those with credit scores as low as 400 to 500. This makes them a primary option for individuals in a difficult financial spot who need immediate liquidity for medical needs but don’t have the luxury of a high FICO score.
They provide loans up to $5,000 with APRs ranging from 15% to 20% for bad credit. While these rates are higher than a prime bank loan, they are a much more manageable alternative to the high-interest payday loans that often trap people in cycles of debt. When comparing these to standard personal loans, the primary advantage here is the accessibility. You are trading a higher interest rate for a significantly higher likelihood of approval. The application is quick, often yielding an approval in just five minutes, which is ideal for urgent cosmetic needs.
Pros:
- Accepts very low credit scores (400+).
- Quick 5-minute approval process.
- Transparent interest rate tiers.
Cons:
- Loan amounts are capped at a relatively low $5,000.
- APR can be high for those with bad credit.
3. FastLendGo
If you are looking for a partner to help navigate personal financing, FastLendGo offers a wide variety of options. They serve several states and provide loans tailored to different credit tiers, including bad, fair, and good credit. This flexibility is refreshing in a market that often defaults to a «one size fits all» approach to lending.
They offer various loan sizes, ranging from small $500 loans up to $5,000. This makes them a great choice for everything from minor dental work to more significant cosmetic adjustments. For example, if you are undergoing a series of laser skin rejuvenation sessions that cost $1,500 each, you can structure your loan to match that specific need rather than taking on a massive, unnecessary debt load. Their focus is on providing a faster way to borrow when cash is needed quickly, making them a strong competitor for quick-turnaround medical expenses.
Pros:
- Flexible loan amounts from $500 to $5,000.
- Options for various credit levels.
- Covers many different states.
Cons:
- Availability is restricted to specific states.
- May not be the best option for very large surgical bills.
4. United
United Bank offers a more traditional banking experience, which can provide a sense of security. While much of their focus is on mortgages and high-yield CDs, they provide essential personal banking services that can support various financial goals, including medical expenses. This is the «old school» approach to financing: building a relationship with an institution to secure better rates over time.
For those with significant savings, they offer competitive returns on CDs, which could be a way to build a fund for surgery. Instead of borrowing, you could use a CD ladder to mature funds exactly when your scheduled procedure arrives. They are FDIC-insured and backed by the full faith and credit of the U.S. Government, offering a level of trust many borrowers crave. However, getting a loan here typically requires a more established banking history and a much higher credit score than the specialized lenders listed elsewhere.
Pros:
- High level of security with FDIC insurance.
- Diverse range of banking products.
- Trusted, established institution.
Cons:
- More traditional requirements may make bad credit financing harder.
- Less specialized for quick-turnaround medical loans compared to others.
5. Ualett
Ualett is a specialized solution designed specifically for the gig economy. If your income is variable because you work through different platforms—such as Uber, DoorDash, or freelance consulting—traditional lenders might struggle to understand your cash flow. Most banks want to see a consistent, month-to-month salary stub. Ualett is built to bridge that specific gap by looking at the actual movement of funds in your account rather than a static employment history.
They offer «GigAdvance» cash advances based on your recent earnings. This provides fast funding when you need it most, allowing independent workers to manage the ups and downs of their unique income streams. If you have a high-earning month due to a surge in freelance work, you can leverage that momentum to secure funds for a procedure before your income fluctuates again. It is a modern solution for a modern workforce that values agility over rigid traditionalism.
Pros:
- Tailored for gig workers with variable income.
- Fast funding based on recent earnings.
- Simple, transparent app-based interface.
Cons:
- Very specific niche may not apply to salaried employees.
- May not provide the large lump sums needed for major surgeries.
6. Quick Credit
Quick Credit is a straightforward option for those in an emergency situation. They provide installment loans for bad credit, with the ability to be approved for up to $3,000 in just a few minutes. This is designed for speed and ease of use, targeting the «immediate need» segment of the market.
The application is fully encrypted and can be completed on a phone, laptop, or tablet. This makes it incredibly convenient for someone who needs to secure funds while on the go—perhaps while sitting in a consultation room or waiting for a surgeon’s callback. They aim to provide cash into your bank account as soon as today, which is vital if your clinic requires a deposit to hold your appointment date.
Pros:
- Extremely fast approval and funding.
- Highly convenient mobile-friendly application.
- Specifically designed for bad credit users.
Cons:
- Loan amounts are limited to $3,000.
- Short-term nature of installment loans can lead to rapid repayment needs.
Comparison of Financing Strategies
Before committing to a lender, it is helpful to categorize your strategy based on your specific financial situation. Not all loans are created equal, and the «best» option depends on your goal: speed, amount, or cost.
| Your Primary Goal | Recommended Approach | Key Consideration |
|---|---|---|
| Maximum Flexibility/Large Amounts | CareCredit / Traditional Bank | Check for high interest if not paid in full. |
| Quick Approval (Low Credit) | Elite Personal Finance / Quick Credit | Be prepared for higher APRs. |
| Managing Variable Income | Ualett | Ensure advances align with your cash flow. |
| Small, Fast Procedures | FastLendGo / Quick Credit | Verify state availability and limits. |
Navigating the Path to Cosmetic Financing
Choosing a lender is not just about the lowest number on the screen. It is about the long-term impact on your life. Before signing anything, ensure you understand whether a lender performs a hard or soft credit check. A soft check allows you to shop around without a penalty, whereas a hard check can ding your score. If you are planning to apply for a mortgage or an auto loan in the next six months, a hard credit check for a cosmetic loan could actually hinder your ability to get that larger loan later.
Avoid the temptation to rush into the first offer just because you are excited about your upcoming procedure. High-interest rates can turn a dream transformation into a financial nightmare. Always compare the total cost of the loan, including all fees and interest, against your monthly budget. A common mistake is looking only at the monthly payment amount. For example, a $2,000 loan with a $100 monthly payment sounds easy, but if the term is 36 months, you are actually paying back $3,600—a massive premium for a relatively small amount.
Finally, always read the fine print regarding late fees and prepayment penalties. Some lenders charge you a fee if you try to pay the loan off early, which effectively punishes you for being financially responsible. In the world of cosmetic procedures, where the goal is to improve your quality of life, ensuring your financing doesn’t decrease it is the most important step in your journey.