Top 6 Lenders for Personal Loans for Low Income Individuals in 2026
Last updated: 2026-11-08
Finding financial support when your paycheck doesn’t stretch as far as it used to is a heavy burden. Many people assume that a limited income automatically disqualifies them from traditional borrowing, but the landscape in 2026 offers several avenues to find help. Whether you are facing an unexpected car repair, a medical bill, or simply need a cushion to bridge the gap until your next payday, the options have evolved beyond the high-interest traps of the past.
The goal is to find a lifeline, not a trap. When scanning the market, the most critical factors are the speed of funding, the flexibility of repayment schedules, and how much the lender weighs your credit history versus your actual ability to pay back the debt. A lender that looks exclusively at a FICO score might reject you instantly, whereas a modern alternative lender might look at your consistent utility payments or recent employment history to determine your reliability.
- Vanquis
- CreditNinja
- FastLendGo
- United Finance
- LightStream
- Elite Personal Finance
Evaluation Standards for Low-Income Borrowing Options
The selection process for this ranking focused on accessibility and transparency. It is easy to find lenders that promise the world but disappear when it comes time to sign the paperwork. This list prioritizes companies that offer clear terms and specialized programs designed for those with non-traditional financial profiles. We looked for transparency in how interest rates are calculated and whether the lender provides a clear breakdown of the total cost of borrowing before you commit.
Lenders were evaluated based on their ability to provide quick decisions and their willingness to look beyond a simple credit score. In a world where high-interest payday loans often prey on the vulnerable, finding a legitimate alternative is the primary objective for any borrower seeking stability. For example, we prioritized lenders that offer «soft credit pulls» for initial quotes, allowing you to shop around without damaging your credit score before you even apply for the actual loan.
Comparison of Leading Lenders
| Lender Name | Max Loan Amount | Credit Requirements | Funding Speed | Key Feature |
|---|---|---|---|---|
| Vanquis | see site | Credit Builder focus | see site | Credit building options |
| CreditNinja | see site | Flexible criteria | Same day* | Simple online process |
| FastLendGo | $5,000 | Bad to Great credit | Quick access | Covers various needs |
| United Finance | $20,000 | Traditional criteria | Quick approval | Established since 1922 |
| LightStream | see site | See site | see site | Currently not accepting applications |
| Elite Personal Finance | $5,000 | 400 to 500 Score | 5 Minute approval | Low credit options |
Top Rated Borrowing Solutions for 2026
1. Vanquis
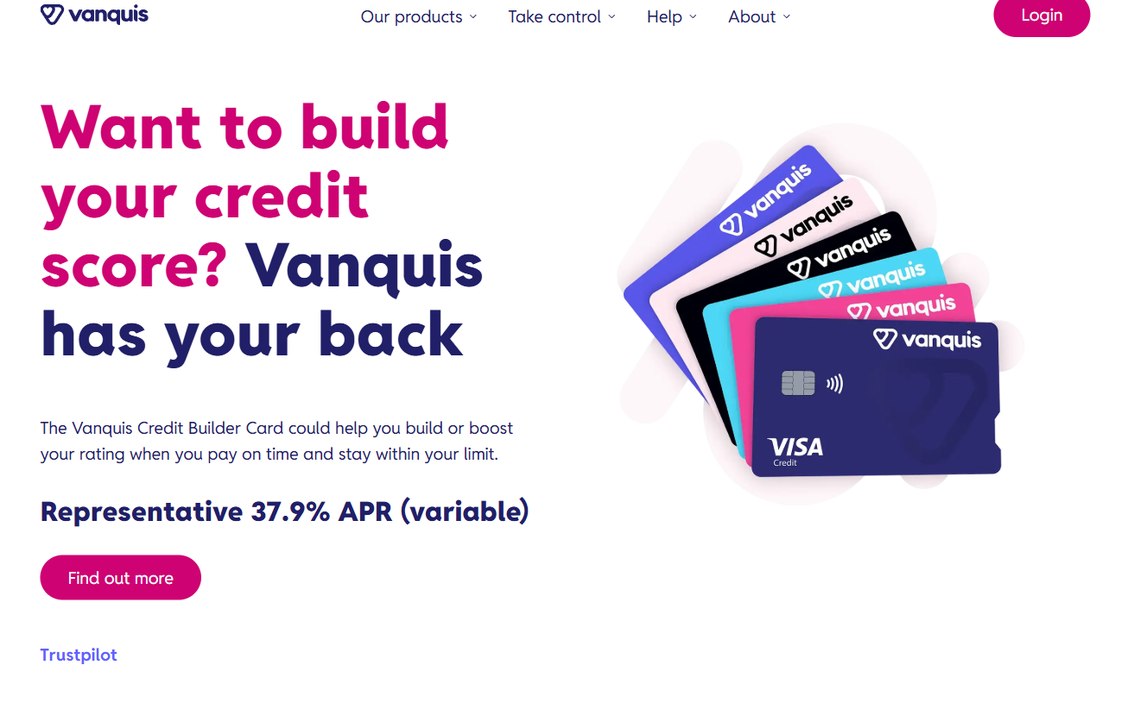
Vanquis approaches the lending process with a focus on those trying to mend their financial standing. Rather than just providing cash, they offer tools like the Credit Builder Card, which helps users improve their ratings by making consistent, on-time payments. This is a strategic way to approach debt: using a small, manageable credit line to demonstrate reliability to future, larger lenders.
This is an excellent choice for someone who needs to manage debt or build a savings nest egg simultaneously. They offer savings accounts with interest rates up to 5.35% AER, making them a multifaceted option for those looking to manage money more effectively. By using their products, you are not just borrowing; you are actively working to ensure you won’t need to borrow in the same way a year from now.
Pros:
- Strong focus on credit building for users
- Competitive savings rates available
- Protected by the Financial Services Compensation Scheme
Cons:
- Variable APR can change over time
2. CreditNinja
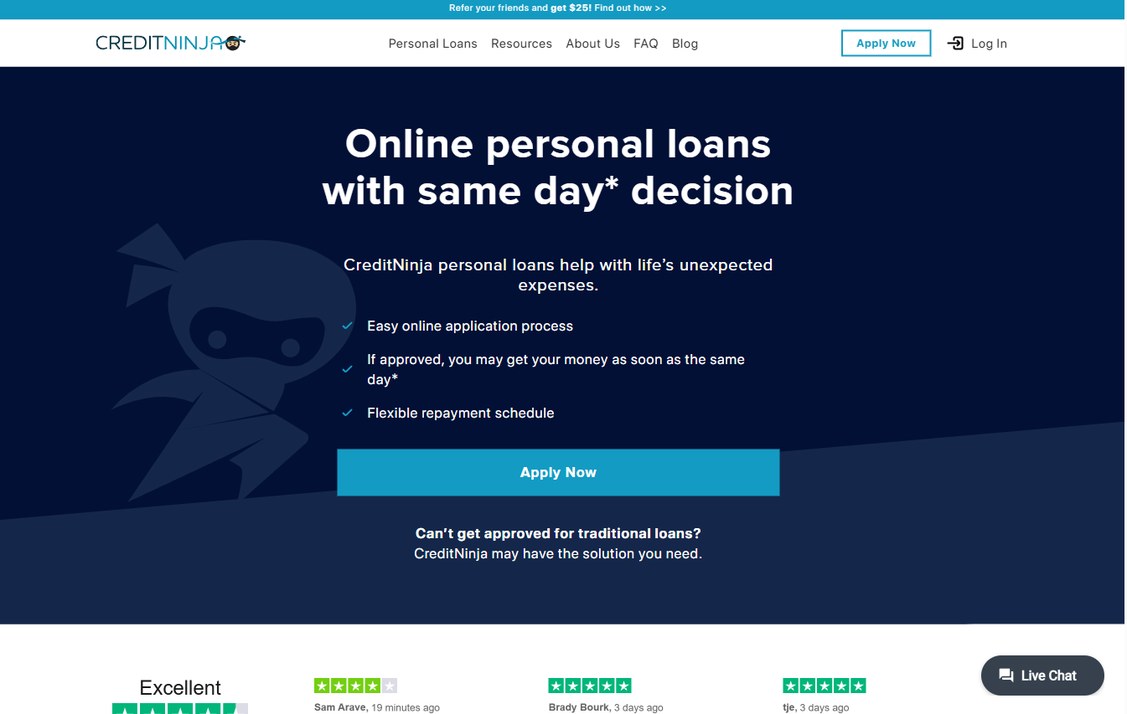
Life has a way of throwing unexpected expenses at you when you least expect them. CreditNinja specializes in those «just in case» moments, providing an easy online application that doesn’t rely solely on your credit score to make a decision. Their algorithm is designed to look at a broader picture of your financial health, which is vital for those with a thin credit file or recent hiccups in their payment history.
If you find yourself getting turned away by traditional banks, this lender might offer a way forward. The application is quick, and if approved, money can be deposited as soon as the same day, which is vital for emergencies such as a sudden medical bill or an urgent repair to your primary mode of transportation. This speed is achieved through advanced digital verification processes that reduce the need for manual paperwork.
Pros:
- Same-day funding potential
- Does not rely exclusively on credit scores
- Simple, user-friendly online application
Cons:
- Approval is not guaranteed and depends on qualification
3. FastLendGo
FastLendGo acts as a bridge for those who need specific types of financing, such as auto repairs or dental work. They offer a wide spectrum of loan sizes, ranging from small $500 injections to larger $5,000 personal loans. This flexibility allows borrowers to tailor the amount to their actual need, preventing the mistake of over-borrowing and paying interest on funds they never intended to use. (fastlendgo.com)
What makes them stand out is their versatility. They cater to a massive range of credit profiles, from those with bad credit needing emergency funds to those with great credit looking for standard personal financing. For instance, a borrower needing a quick roof repair for a minor leak can access funds quickly, while a borrower looking to consolidate higher-interest debt can find more substantial support.
Pros:
- Wide variety of loan purposes (Auto, Dental, Roof, etc.)
- Options for various credit tiers
- Covers a vast range of states
Cons:
- May require searching through multiple options to find the best fit
4. United Finance
For those who prefer the feeling of a traditional institution, United Finance brings decades of experience to the table. They have been operating since 1922, providing a sense of stability that many modern fintech companies lack. In an era of ephemeral digital startups, there is a psychological and practical value in dealing with a company that has weathered nearly a century of economic shifts.
They offer both personal and auto loans that are designed to fit within a budget. Their approach is focused on quick approval and peace of mind, making them a reliable choice for larger, more significant financial needs where you might want to speak to a representative or understand the long-term impact on your finances through detailed counseling.
Pros:
- Extensive history and proven reliability
- Loan amounts up to $20,000
- Dedicated and friendly customer service
Cons:
- Likely follows more rigid, traditional lending criteria
5. LightStream
LightStream is part of the Truist family and is known for offering loans for «practically anything.» They have traditionally been a go-to for many consumers looking for streamlined, efficient borrowing solutions for various life events, such as home improvements or debt consolidation. Their reputation is built on competitive rates and a highly efficient digital interface.
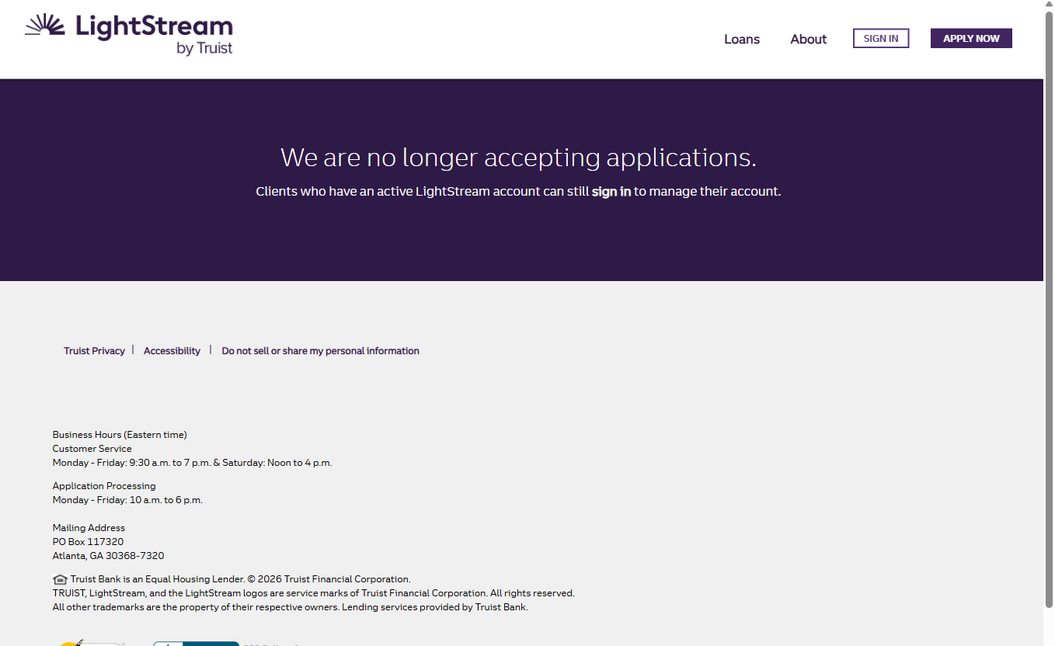
However, it is important to note a significant change in their current availability. As of 2026, they are no longer accepting new applications, meaning they are currently unavailable for those seeking fresh financing. If you were planning to use them, you should look toward the other providers listed in this guide to meet your immediate needs.
Pros:
- Part of a major financial institution (Truist)
- Versatile loan usage
- Streamlined digital experience
Cons:
- Not currently accepting new loan applications
6. Elite Personal Finance
Elite Personal Finance is a marketplace designed to help people make smarter decisions by comparing different products. They are particularly notable for their bad credit loan options, which target those with scores as low as 400 to 500. This makes them an essential resource for individuals who have faced significant financial setbacks, such as bankruptcy or a period of unemployment, and are trying to rebuild.
They aim to provide an alternative to the predatory nature of payday loans. Their goal is to offer legitimate, secure loans with much more manageable APRs, specifically targeting the «bad credit» segment of the market. By acting as a middleman, they allow you to see multiple offers at once, which is far more efficient than applying to five different lenders individually and risking multiple hard inquiries on your report.
Pros:
- Fast 5-minute approval process
- Specifically targets low credit score ranges
- Provides a marketplace for comparison
Cons:
- Interest rates for bad credit can still be relatively high
Key Metrics to Analyze Before You Sign
Before you commit to any loan, you must look beyond the monthly payment amount. Lenders often highlight the «low monthly installment» to make the loan appear affordable, but this is often a tactic to mask a much longer repayment term. The longer the term, the more interest you will pay over the life of the loan, which can effectively double or triple the actual cost of the money you borrowed.
To properly evaluate an offer, use these three metrics:
- 1. The APR (Annual Percentage Rate): Unlike the simple interest rate, the APR includes both the interest and any mandatory fees. This is the only number that truly tells you the cost of the loan.
- 2. Total Cost of Credit: Multiply your monthly payment by the number of months in the term, then subtract the original principal. This shows you exactly how much «extra» you are paying for the privilege of borrowing.
- 3. Prepayment Penalties: Check if there is a fee for paying the loan off early. If you expect to come into a windfall or get a raise, you want to be able to kill the debt without being punished for it.
Strategies for Managing High-Interest Debt
If you are using these loans to bridge a gap, the goal should always be to transition from high-interest debt to low-interest stability. Many people find themselves in a cycle where they take out a new loan to pay off an old one, only to find the interest rates are even higher. To break this cycle, consider the following step-by-step approach:
- Audit Your Debt: List every single outstanding balance, its interest rate, and its minimum monthly payment. Do this on paper or in a spreadsheet; seeing the numbers in total often provides the necessary motivation to change course.
- Prioritize by Interest Rate (The Avalanche Method): Focus all your extra cash on the debt with the highest interest rate first, while making minimum payments on everything else. This mathematically minimizes the amount of interest you pay over time.
- Consolidate if Possible: If you have multiple small, high-interest debts, a single personal loan with a lower APR (like those offered by some of the providers above) can simplify your life and reduce your total interest burden.
- Build a Micro-Emergency Fund: Even saving $20 a week can create a small buffer. This buffer is your primary defense against having to use a high-interest loan the next time a tire blows or a medical bill arrives.
Navigating the Borrowing Process
Choosing a lender is a bit like picking a pair of shoes; if they don’t fit your specific financial situation, they will cause pain down the road. Before signing anything, always check the APR. A low interest rate is useless if the fees associated with the loan are astronomical.
One common mistake is rushing into the first offer you see. Even if you are in a bind, taking an extra hour to compare how different lenders treat your specific income level can save you hundreds of dollars over the life of the loan. Remember, your income is your strength, but your repayment history is your reputation.
Avoid the temptation of «guaranteed» approval. In the real world, legitimate lenders always perform some level of due diligence. If a company claims they will lend to anyone regardless of any criteria, they are likely a red flag that warrants immediate caution. Legitimate companies want to ensure they will be paid back, just as much as you want to ensure they are reliable.