Top 6 Lenders for a 520 Credit Score Personal Loan in 2026
Last updated: 2026-11-08
Walking into a bank with a 520 credit score often feels like trying to enter a VIP club without an invitation. You know the door is there, but the bouncers seem uninterested in your story. It is a stressful position to be in, especially when urgent expenses demand immediate cash to keep your life moving forward.
Finding the right lender requires looking past the flashy advertisements. You need to distinguish between helpful financial tools and predatory traps that lead to a cycle of debt. This ranking focuses on finding stability, assessing how much cash is actually available, and determining which lenders might actually take a chance on a lower score.
- Max Cash
- JetzLoan
- Upgrade
- Truist
- Citi
- Navy Federal Credit Union
How These Lenders Were Evaluated for Low Credit Scores
The comparison process focused heavily on accessibility for borrowers in the subprime and fair credit categories. Since a 520 score is significantly below the «good» threshold, many traditional bank products are off the table. The evaluation prioritized lenders that offer specialized paths for those struggling with high credit utilization or previous payment hiccups.
Speed of funding and transparency regarding loan amounts were the secondary pillars of this research. A lender that promises a quick turnaround but hides massive interest rates is not helpful. Therefore, the selection process looked at the range of funds available and the specific types of products offered to ensure a diverse list for different needs.
| Lender Name | Loan Amounts | Credit Requirements | Funding Speed | Special Features |
|---|---|---|---|---|
| Max Cash | $250 – $10,000+ | Bad Credit Options | Minutes | Title & Installment Loans |
| JetzLoan | See site | See site | See site | See site |
| Upgrade | Up to $50,000 | Check your rate | Fast funding | Debt Consolidation |
| Truist | See site | See site | See site | No overdraft fees |
| Citi | See site | See site | See site | Relationship tiers |
| Navy Federal | See site | Membership required | 90-day preapproval | Military/Veteran focus |
1. MAX CASH
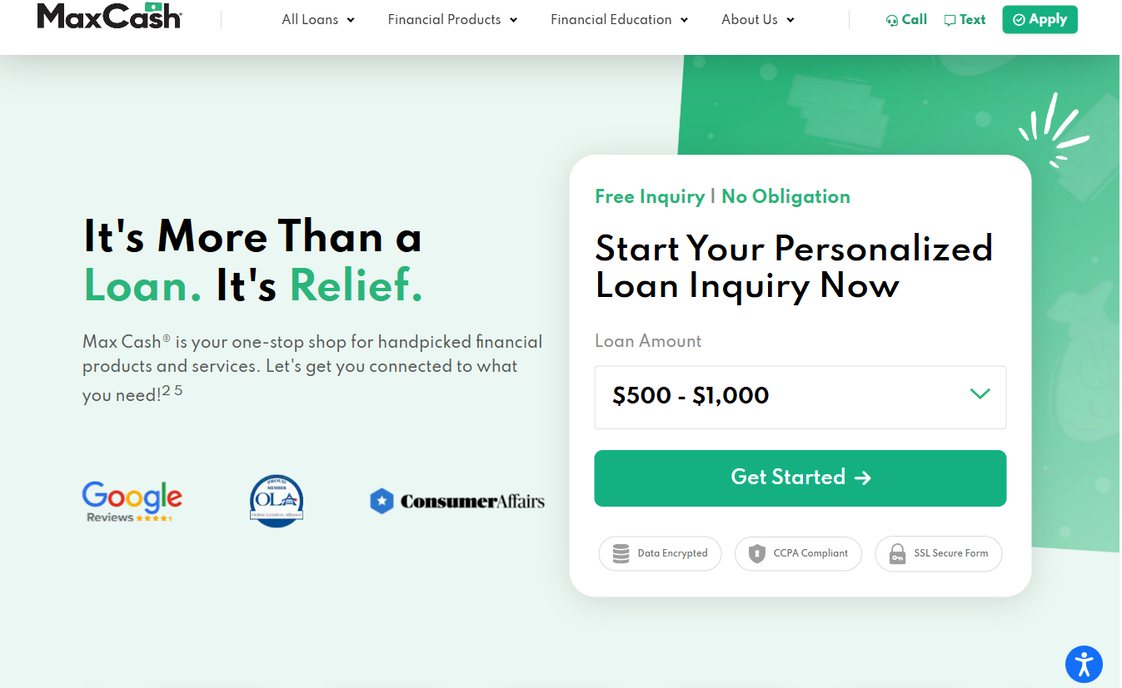
When you are staring at a mounting pile of bills and your score is sitting at 520, you need a lifeline, not a lecture. Max Cash acts as a specialized hub for those who might be ignored by the big-name banks. They offer a variety of products ranging from small cash advances to larger installment loans.
This lender is particularly suited for those needing immediate relief through title loans or personal installments. Because they cater to a wide spectrum of needs, you can find specific products designed for various financial emergencies. It is a one-stop shop for people who need to get connected to something right now.
Pros:
- Covers a wide range of amounts from $250 up to $10,000 or more.
- Offers specialized title and installment loan options.
- Fast process to find a personalized match.
Cons:
- Focuses on high-risk products which may carry higher costs.
2. JETZLOAN
Navigating the landscape of alternative lending can feel like walking through a fog. JetzLoan enters the market as a contender for those seeking specific, tailored financial solutions. While they occupy a niche space, they are included for their presence in the modern lending ecosystem.
Finding the right fit with a 520 score often requires looking at unconventional lenders. If traditional routes are blocked, exploring different platforms can provide a different perspective on what you might qualify for. It is always wise to check their specific terms before signing anything.
Pros:
- Provides an alternative to traditional banking.
- Offers specialized lending research.
Cons:
- Specific terms and requirements are highly variable.
3. UPGRADE
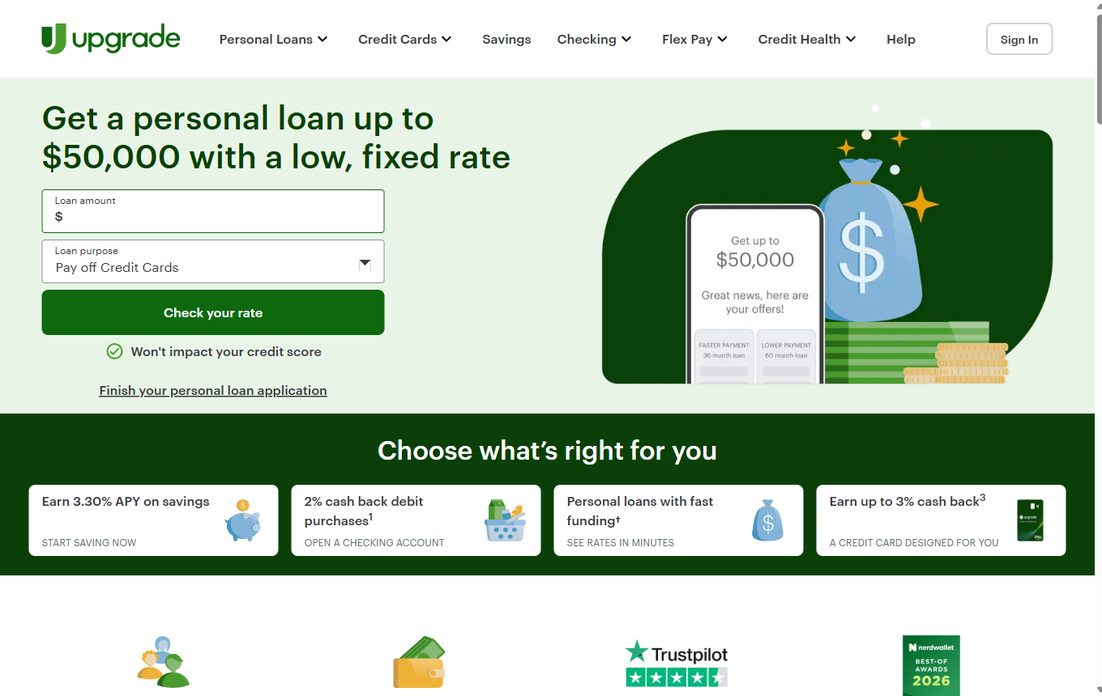
Upgrade serves a different crowd, often focusing on those looking to consolidate debt or make significant life purchases. While they are known for their ability to help people with various credit profiles, they are a more structured option compared to quick-cash lenders. They offer a path to manage debt more effectively.
If you are looking to clean up your financial life by paying off credit cards, this might be a strategic move. They provide a way to check your rate without a heavy impact on your credit score, which is vital when you are trying to rebuild from a 520.
Pros:
- High loan amounts reaching up to $50,000.
- No impact on credit score when checking rates.
- Useful for debt consolidation and large purchases.
Cons:
- May require a higher score for the best fixed rates.
4. TRUIST
Truist represents the more traditional banking side of the spectrum. While a 520 score might make standard personal loans a challenge, Truist offers a suite of services that help manage your day-to-day finances. Their focus is often on long-term stability and relationship banking.
They provide features like the Truist One Checking account, which aims to reduce the stress of overdraft fees. For someone struggling with credit, avoiding unexpected fees can be the difference between staying afloat and sinking further into debt.
Pros:
- Focus on reducing overdraft fees for clients.
- Comprehensive suite of banking and lending services.
- Strong presence for personal and small business needs.
Cons:
- Traditional credit requirements can be strict for low scores.
5. CITI
Citi is a heavyweight in the financial world, offering everything from credit cards to mortgages. For those with a 520 score, their standard high-tier products might be out of reach, but their ecosystem offers various ways to grow your wealth over time. They are built for the long game.
The bank utilizes relationship tiers that can reward customers who maintain multiple accounts. While you might not start at the top, using a major institution can provide the structure needed to eventually climb back up the credit ladder.
Pros:
- Extensive range of financial products and investing options.
- Potential for higher savings rates through relationship tiers.
- Highly established and stable institution.
Cons:
- High-end benefits are typically reserved for higher credit tiers.
6. NAVY FEDERAL CREDIT UNION
Navy Federal is a unique player, specifically catering to the military community, veterans, and their families. If you fall into this category, you have access to a much more supportive environment than the average consumer. They understand the unique financial stresses that service members often face.
One of their standout features is the 90-day preapproval process for auto loans. This gives you a level of latitude to shop for a vehicle without the immediate pressure of a hard credit check, making it a great tool for those managing their credit carefully.
Pros:
- Exceptional support for military and veterans.
- 90-day preapproval window for auto loans.
- Comprehensive range of specialized credit union services.
Cons:
- Strict membership requirements limit the customer base.
Navigating the Path to Better Credit
Avoiding the «borrow/repay/rinse/repeat» cycle is the most important rule in finance. Payday loans might seem like a quick fix when you are in a pinch, but they often act as a trap. These predatory products can lead to a spiral of debt that is incredibly difficult to escape.
Instead of reaching for the quickest, most expensive cash, look for lenders that offer a way to improve your situation. This might mean choosing a debt consolidation loan from a provider like Upgrade or building a relationship with a credit union. Small, consistent steps are better than one giant, expensive leap.
Before signing any agreement, read the fine print regarding interest rates and fees. A loan that looks small on paper can become a mountain of debt if the interest rates are not clearly understood. Knowledge is your best defense against high-cost credit products.