Top 6 Lenders for a 12 Year Personal Loan in 2026
Last updated: 2026-11-08
Finding a lender willing to stretch a loan out over a decade is a bit like hunting for a vintage car in a modern dealership. Most lenders prefer shorter windows, usually 36 to 60 months. They want to minimize their own risk and keep their capital moving. However, long-term financing remains a vital tool for massive home renovations, like a complete kitchen overhaul or a new roof. It is also essential for consolidating substantial debt piles that would take years to chip away at through standard credit card payments. When you stretch a term to 120 months or longer, you are negotiating with time itself.
This ranking helps borrowers sort through the complex options for long-term debt. When choosing a lender for such a marathon commitment, you have to weigh the total interest paid against the monthly breathing room provided by lower payments. It is a balancing act of cash flow and long-term cost. For instance, a \$20,000 loan at a 10% interest rate over three years requires a monthly payment of roughly \$645. Stretching that same loan to ten years drops the payment to approximately \$264. That monthly difference of nearly \$400 provides immense lifestyle flexibility, but it also means you are paying significantly more in interest over the life of the loan. This is the core tension of long-term lending.
- JetzLoan
- SoFi
- Addition Financial
- World Finance
- OneMain Financial
- EZMax Loans
Evaluating Long-Term Lending Options
The evaluation process focused on how these lenders handle extended repayment schedules. A 12-year term is an outlier in the personal loan market. Most lenders find their «sweet spot» between 3 and 5 years. Because of this, we looked closely at interest rate stability and the flexibility of repayment structures. In a long-term scenario, even a tiny fluctuation in your annual percentage rate (APR) can result in thousands of dollars of difference over a decade. We looked specifically at whether lenders offer fixed rates that protect you from market volatility or variable rates that could spike and jeopardize your budget years down the line.
Lenders were assessed based on their accessibility for different credit profiles. Some institutions cater to the elite with low rates and require a pristine credit history, often looking for a FICO score above 740. Others exist specifically to provide a lifeline to those with less-than-perfect credit. These lenders might use alternative data like income verification or employment history to justify the risk. Understanding where you fall on the spectrum determines which of these six names should be your first call. Are you a «prime» borrower looking for the lowest possible interest rate to minimize total cost, or are you a «subprime» borrower looking for maximum approval probability regardless of the cost?
| Lender Name | Loan Amounts | Terms | Speed of Funds | Credit Requirements |
|---|---|---|---|---|
| JetzLoan | see site | see site | see site | see site |
| SoFi | see site | see site | see site | see site |
| Addition Financial | see site | see site | see site | see site |
| World Finance | from $450 | see site | same-day | no matter your credit score |
| OneMain Financial | $1,500 – $35,000 | 24-60 months | as soon as 1 hour | see site |
| EZMax Loans | $200 – $2,000 | see site | minutes | see site |
The 2026 Lending Leaderboard
1. JetzLoan
JetzLoan occupies the top spot for those specifically seeking specialized long-term structures. They aim to fill the gaps left by traditional banks that often shy away from the extended timelines required for major life milestones. While a standard bank might balk at a 10-year personal loan due to the high probability of borrower life changes, such as job loss or relocation, JetzLoan has built its model around these extended horizons.
This lender is a strong match for borrowers who have done their math and know exactly how much monthly relief they need. They focus on the nuances of long-term debt management without the rigid constraints of standard consumer products. Their underwriting process often considers the long-term stability of your income rather than just a snapshot of your current debt-to-income ratio. This is crucial when you are planning for a decade-long repayment cycle.
Pros:
- Specialized focus on long-term needs
- Niche market positioning
Cons:
- Limited public data on specific rates
2. SoFi
SoFi is a heavyweight in the digital finance arena, offering a comprehensive suite of services. From high-yield savings to complex investing tools, they aim to be a one-stop shop for a modern, tech-savvy lifestyle. Their platform is designed to integrate your entire financial life. You can see how a new loan might impact your overall net worth in real-time.
They are an excellent choice for professionals who want their banking, loans, and investments under one digital roof. Their interface is slick, making the management of long-term debt feel much less like a chore. For example, their automated tools can help you track your progress toward paying off the principal. Their mobile app allows for instant payments, which can be a subtle but effective way to shave months off a long-term loan through small, frequent overpayments.
Pros:
- All-in-one financial ecosystem
- Highly integrated digital tools
Cons:
- Likely requires a strong credit profile
3. Addition Financial
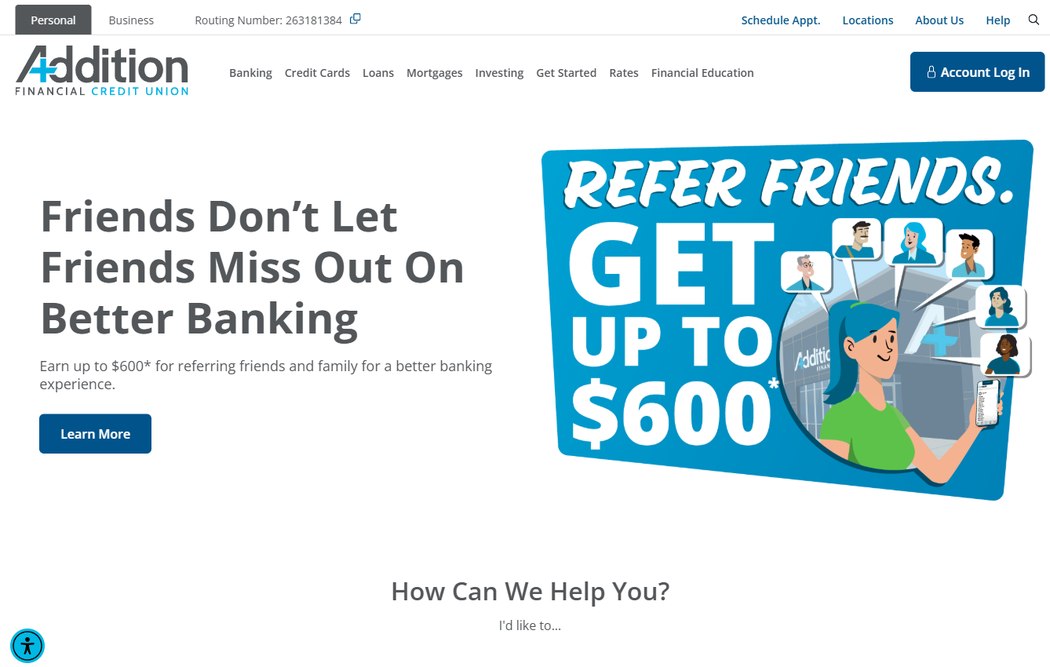
Addition Financial operates as a credit union, which fundamentally changes the relationship between the borrower and the lender. Because they are member-owned, the focus often shifts toward competitive rates and community-centric service. Unlike a corporate bank that answers to shareholders looking for quarterly profit spikes, a credit union answers to you.
They offer a variety of products, including car loans and business growth options. For someone looking for a personal loan with a long horizon, their cooperative structure can often lead to more favorable terms than a standard commercial bank. This is especially true if you maintain a healthy relationship with the institution. They may offer «member perks» such as slightly lower interest rates or waived administrative fees that can save significant money over a ten-year period.
Pros:
- Competitive rates for members
- Diverse financial product range
Cons:
- Membership may be required
4. World Finance
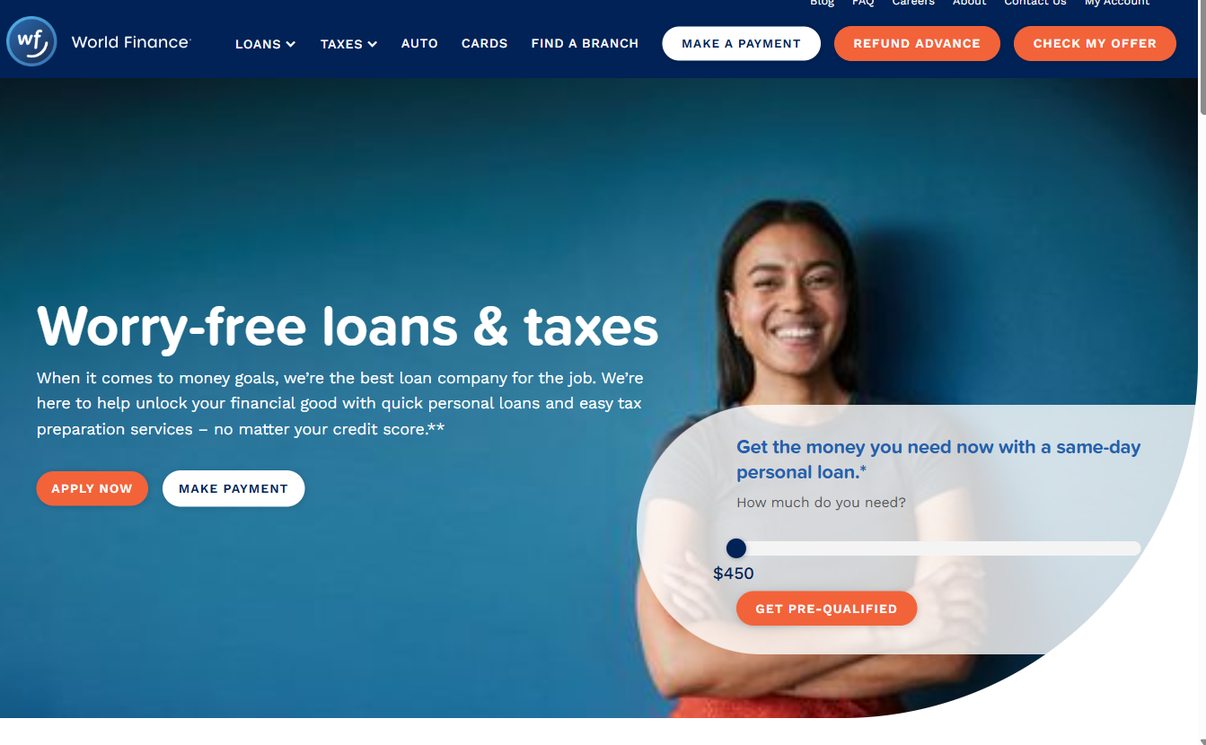
World Finance is the go-to option for those who need immediate liquidity regardless of their current credit standing. They specialize in helping people unlock their financial potential through quick, accessible personal loans. This is a vital service for those who may have been excluded from traditional banking due to historical credit hiccups or a thin credit file.
If you are facing an unexpected expense and need funds by the end of the day, this is where you look. They also provide tax preparation services, making them a multifaceted option for those navigating tricky financial seasons. While their interest rates may not be the lowest in the market, the ability to secure funding when traditional doors are closed is a value proposition that many borrowers find indispensable.
Pros:
- Same-day personal loans available
- No credit score barriers to apply
Cons:
- Terms may be less flexible for long-term use
5. OneMain Financial
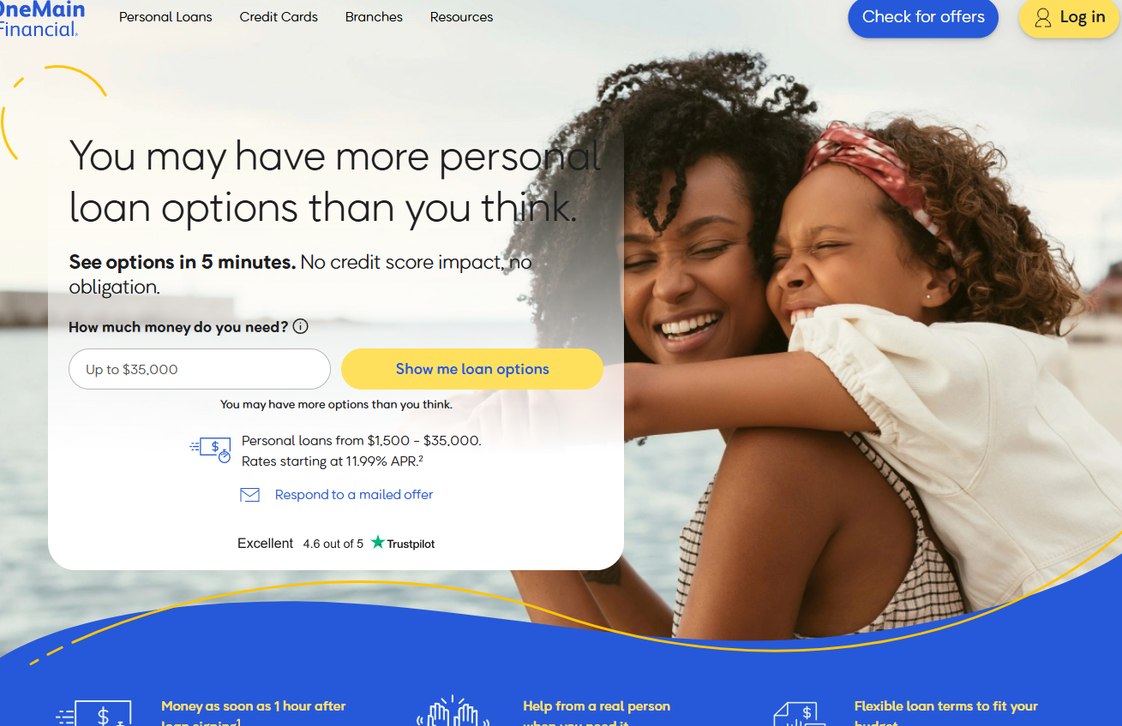
OneMain Financial bridges the gap between digital ease and human connection. With over 1,300 physical branches, they offer a level of accessibility that online-only lenders simply cannot match when things get complicated. If you have a specific question about your repayment schedule or need to discuss a hardship deferment, walking into a branch to speak with a person can provide a sense of security that an automated chat box cannot.
They are particularly useful for those who want to see options quickly without impacting their credit score during the initial check. Their «soft pull» technology allows you to gauge your eligibility and estimated rate before you commit to a «hard pull» that stays on your report. Their ability to fund a loan within an hour of signing makes them a speed leader in the mid-range loan category.
Pros:
- Extensive branch network for in-person help
- Fast funding after signing
Cons:
- Terms generally capped at 60 months
6. EZMax Loans
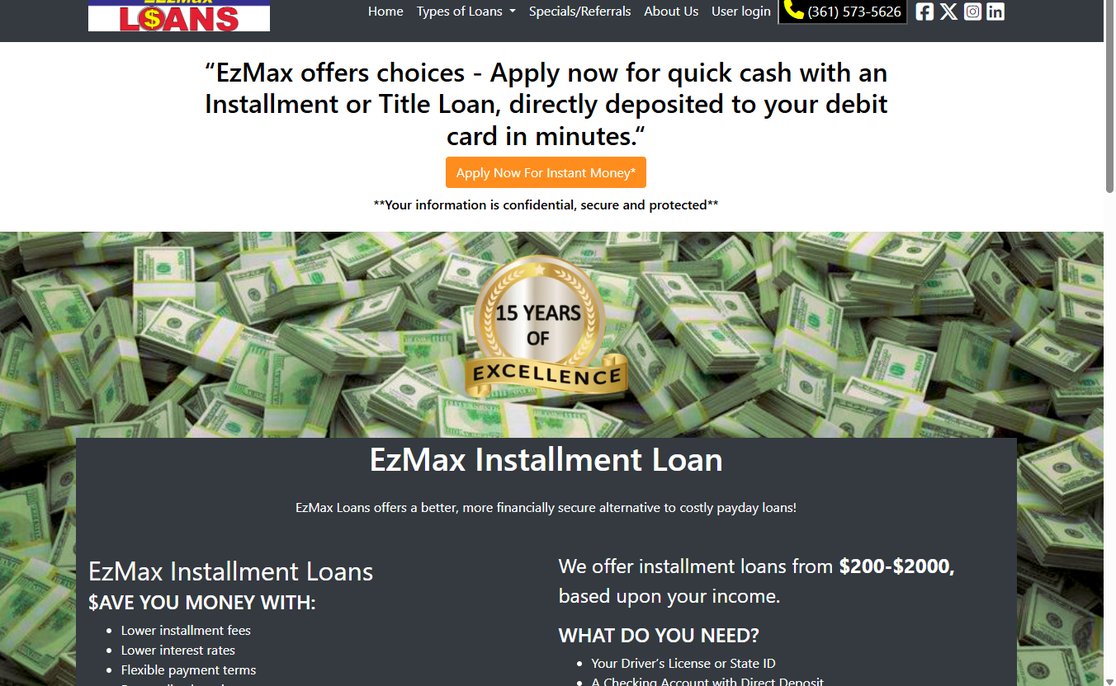
EZMax Loans serves a very specific purpose: providing quick cash through installment or title loans. They position themselves as a more secure and affordable alternative to the predatory nature of traditional payday loans. Instead of the astronomical 400% APRs often found in payday lending, EZMax offers more structured installment plans that allow for a more predictable repayment schedule.
With loans ranging from \$200 to \$2,000, this is not a tool for a decade-long renovation. It is a tool for the «right now» moments, like an emergency car repair or an urgent utility bill that cannot wait until next month. It is a short-term bridge to get you through a gap in your cash flow without the downward spiral of traditional payday lending.
Pros:
- Rapid direct deposit to debit cards
- Lower fees than payday loans
Cons:
- Very low maximum loan amounts
Strategic Debt Management for Long-Term Borrowers
When committing to a loan that spans many years, your strategy for repayment must be just as long-term as the debt itself. Simply making the minimum payment every month is the default path, but it is rarely the most efficient. To maximize your financial health, consider the following strategic steps:
- The Round-Up Method: If your monthly payment is \$264, try to pay \$300. That extra \$36 might seem negligible in your monthly budget, but over ten years, those small increments can shave nearly a year off your term and save you hundreds in interest.
- Lump-Sum Windfalls: Treat tax refunds, work bonuses, or monetary gifts as «debt accelerators.» Applying a \$1,000 bonus directly to your loan principal can have a massive compounding effect on the total interest you avoid.
- Annual Interest Rate Audit: Every 24 months, check the current market rates. If rates have dropped significantly, it may be worth the cost of a refinance to lower your APR, effectively «resetting» your debt at a more favorable rate.
Understanding the Impact of Inflation on Debt
One often overlooked advantage of long-term borrowing is the role of inflation. While inflation is generally viewed as an economic negative, it can actually work in the favor of a borrower with a fixed-rate long-term loan. When you take out a loan today, you are borrowing «expensive» dollars. These are dollars that have significant purchasing power. As the years pass and inflation erodes the value of the dollar, the «real» value of your fixed monthly payment decreases.
For example, if you owe \$300 a month, that \$300 might represent a larger portion of your income today than it will in the year 2030. As wages typically rise with inflation, your debt becomes «cheaper» to service over time. This is a key reason why many investors prefer to carry fixed-rate debt; it is essentially a way to pay back your debt with «cheaper» future money. However, this benefit only applies to fixed-rate loans. If you have a variable-rate loan, inflation often leads to central bank rate hikes, which can increase your monthly payments and negate this advantage entirely.
Avoiding Common Pitfalls in Long-Term Borrowing
The biggest mistake anyone can make with a 12-year loan is ignoring the «total cost of interest» trap. While a low monthly payment looks beautiful on paper, paying interest for twelve years can result in a total repayment amount that is double the original principal. You must run the numbers on a loan calculator before signing; never rely solely on the monthly payment figure provided by a salesperson or a website’s quick-quote tool.
Always check for prepayment penalties. If you find yourself with extra cash in three years, you want the ability to wipe out that debt without being charged a massive fee. Freedom from debt is the goal, so ensure your lender doesn’t make it expensive to be responsible. Some lenders bake a «yield maintenance» clause into their contracts to ensure they get their expected interest profit, which can make paying off a loan early prohibitively expensive.
Finally, ensure your budget can withstand a decade of inflation and life changes. A payment that feels easy today might feel burdensome in five years if your income fluctuates or if your household expenses rise. Always aim for a monthly payment that leaves you plenty of room to breathe. If your debt-to-income ratio is already high, a long-term loan might provide temporary relief but could leave you vulnerable to any future economic downturns.