The 7 Best No Credit Check Home Improvement Loans for 2026
Last updated: 2026-11-09
Finding the right funding for a kitchen remodel or a new deck can feel like navigating a dense fog. Many homeowners assume a bruised credit score is a total roadblock to upgrading their living space. However, the lending landscape in 2026 offers several paths forward for those who cannot secure traditional bank financing. Whether you are dealing with a sudden leak in the roof that requires immediate intervention or a planned expansion of your living area, the financial tools available today are more diverse than ever before.
When selecting a provider, the most important factors are speed, total cost of capital, and the impact on your credit profile. Some lenders offer quick cash for urgent repairs, while others provide massive pools of capital for major structural changes. For example, a homeowner needing a quick $3,000 for a broken HVAC unit requires a fundamentally different product than a homeowner looking to build a $75,000 detached garage. Knowing which tool fits your specific project is the key to avoiding a debt trap. Using a high-interest personal loan for a 30-year structural improvement is often a strategic error, just as applying for a massive equity loan for a minor cosmetic fix is inefficient.
- HFS Financial
- JetzLoan
- Cash Store
- NetCredit
- Minute Loan Center
- Truist
- Tower Loan
How These Lending Options Were Evaluated
The evaluation process focused on how these lenders handle applicants with non-traditional credit profiles. Each entity was scrutinized based on their stated willingness to work with various credit tiers and the specific types of home projects they cover. Speed of funding was also a major metric for those facing emergency repairs. We analyzed the «friction points» in the application process—looking at how many days elapsed from initial inquiry to funds being available in a bank account.
Lenders were categorized by their primary strength, such as large-scale renovations or quick installment-based solutions. While some specialize in massive backyard transformations, others are designed to bridge the gap for minor indoor fixes. For instance, we compared «soft pull» eligibility checks against «hard pull» requirements to determine which lenders allow for risk-free comparison shopping. The goal was to identify which providers offer the most flexibility for diverse homeowner needs, ranging from the budget-conscious renter to the established homeowner with significant equity but a recent credit dip.
| Lender Name | Loan Amounts | Terms | Funding Speed | Credit Requirements |
|---|---|---|---|---|
| HFS Financial | Up to $450K | Up to 30 Years | see site | Inquiring won’t impact credit |
| JetzLoan | see site | see site | see site | see site |
| Cash Store | see site | see site | see site | see site |
| NetCredit | Up to $10,000 | Flexible | Same-day available | Check eligibility |
| Minute Loan Center | see site | see site | Same-day | Fair credit ok |
| Truist | see site | see site | see site | see site |
| Tower Loan | see site | see site | see site | see site |
Top Rated Home Improvement Lenders for 2026
1. HFS Financial
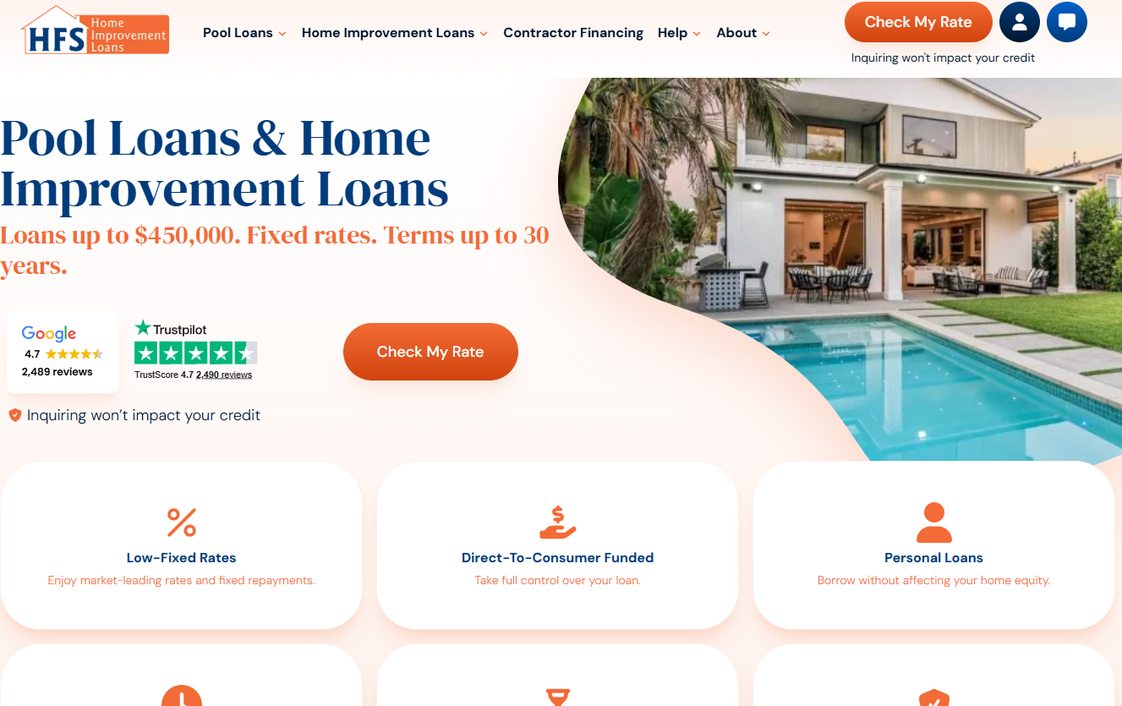
This lender stands out for major structural transformations. Whether you are looking to install a massive swimming pool or rebuild a complete kitchen, they handle the heavy lifting. Their specialized focus on large-scale projects makes them a powerhouse for significant property value increases. Unlike standard personal loans that might cap out at $50,000, HFS is built for the high-ticket items that redefine a property’s footprint.
They offer massive loan amounts reaching up to $450,000. This is ideal for homeowners tackling ADU (Accessory Dwelling Unit) financing or extensive roofing and landscaping projects that require professional contractors and multiple stages of disbursement. Because they specialize in these large sums, their underwriting process is designed to accommodate the complexity of high-value home improvements. Since inquiring about their rates won’t impact your credit score, you can explore your options without any immediate risk to your standing.
Pros:
- Extremely high loan caps up to $450,000.
- Long-term flexibility with 30-year terms.
- Wide variety of project types including solar and HVAC.
Cons:
- May not be suitable for very small, quick cash needs.
2. JetzLoan
JetzLoan occupies a unique niche in the modern lending market. They focus on efficiency, catering to those who need to move quickly on a renovation. Their model is built around streamlined processes that reduce the friction often found in traditional banking institutions. While a traditional bank might require weeks of document verification, JetzLoan is engineered for the modern, fast-paced renovation cycle.
This is a strong choice for the decisive homeowner. If you have found a contractor and need to secure funds to lock in a price before a seasonal price hike, their approach helps maintain that momentum. They aim to bridge the gap between traditional loans and immediate cash needs, making them particularly useful for mid-range projects like bathroom upgrades or deck resurfacing where the contractor requires a deposit upfront to secure the crew.
Pros:
- Streamlined application process.
- Focus on speed and efficiency.
Cons:
- Specific product details require direct inquiry.
3. Cash Store
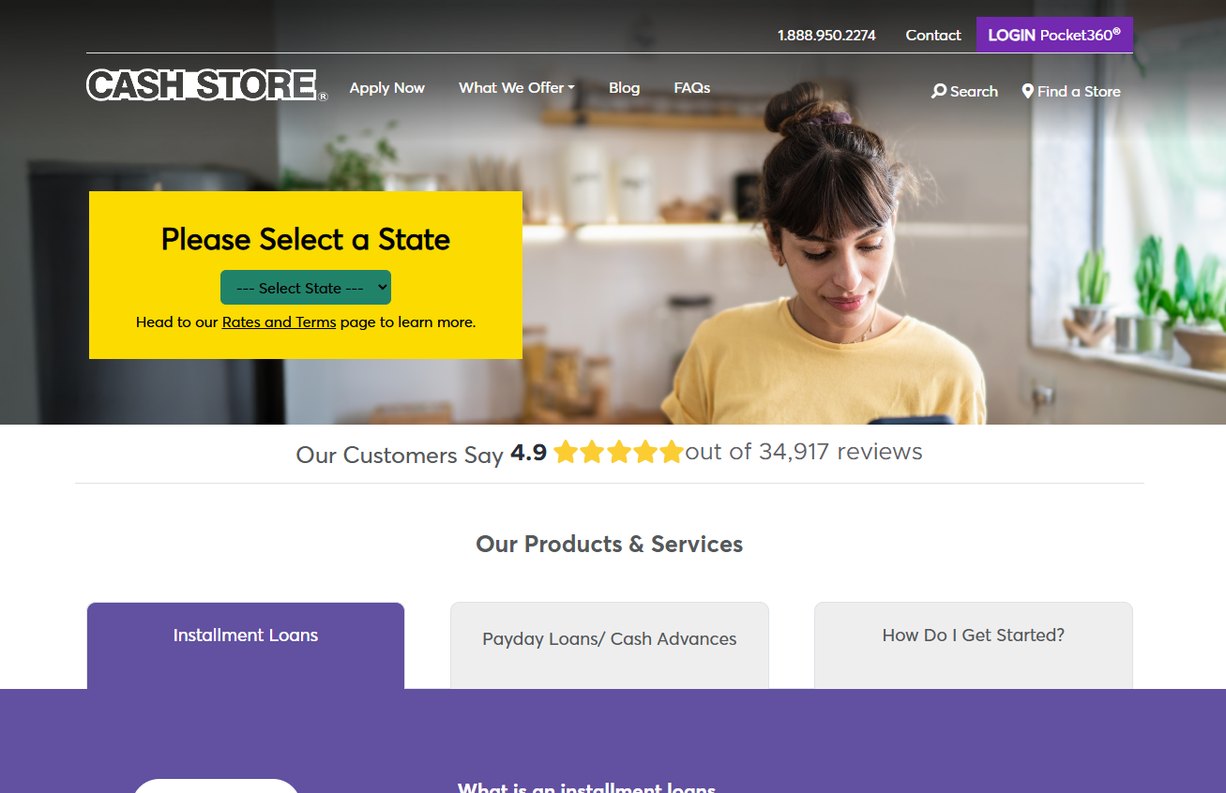
When a home repair becomes an emergency, sometimes you need an alternative to a standard payday loan. Cash Store provides installment loans that act as a more structured way to manage immediate cash flow. They operate in several states, including Texas and Wisconsin. This structured approach is critical; unlike a single-payment payday loan that can lead to a cycle of debt, an installment loan allows you to pay back the principal over a set schedule.
This option is best for smaller, urgent fixes that cannot wait for a traditional mortgage modification or a home equity line of credit (HELOC) approval. If a water heater fails on a Sunday, you may not have time for a two-week bank review. Cash Store serves as a fallback option for those who need liquidity immediately but want something more stable than a high-interest short-term loan.
Pros:
- Provides an alternative to payday loans.
- Installment-based structure for predictability.
- Wide geographic availability.
Cons:
- Higher interest rates compared to traditional bank loans.
4. NetCredit
NetCredit focuses on the person behind the paperwork. They use advanced algorithms to look beyond a single FICO score, acknowledging that a number in a database doesn’t tell the whole story. For example, a person might have a low score due to a medical bill or a past student loan issue, but they may have a perfectly stable income and a consistent history of on-time utility payments. NetCredit’s model attempts to capture that nuance.
With loans reaching up to $10,000, they are perfect for smaller indoor updates like replacing kitchen appliances, upgrading light fixtures, or refreshing interior paint. You can check your eligibility without affecting your credit score, which is a vital safety net when you are in the research phase. Same-day funding is also an option for those in a hurry, providing a significant advantage for minor, non-structural repairs.
Pros:
- No impact on FICO score during eligibility check.
- Fast same-day funding availability.
- Loans up to $10,000 for smaller projects.
Cons:
- Loan amounts may be too low for large structural renovations.
5. Minute Loan Center
Speed is the primary language spoken here. This provider is built for the homeowner who needs cash deposited almost instantly. They offer fast approval even for those with fair credit, making them highly accessible for quick fixes. This is particularly useful in the «preventative maintenance» category—fixing a minor leak before it turns into a full-blown ceiling collapse.
The process is designed to be incredibly simple: apply, get approved, and receive your deposit via direct deposit. This eliminates the need for physical checks or waiting for a bank’s internal processing cycle. It is a highly efficient tool for those who need to bypass the long waiting periods typical of traditional home equity loans or construction loans.
Pros:
- Instant online application and approval.
- Same-day deposit via direct deposit.
- No hidden fees or credit pulls for initial application.
Cons:
- May not offer the most competitive rates for long-term debt.
6. Truist
For those looking for a more traditional banking relationship, Truist offers a comprehensive suite of services. They are a massive institution that handles everything from basic checking to complex mortgage and investment products. They represent the established financial standard for homeowners who have a long-term vision for their property and their personal finances.
If you have a stable financial history and are looking for more integrated services like checking and savings, Truist is a solid choice. They offer the security of a large bank, which can provide peace of mind for very large, long-term investments. If you are planning a major remodel that will take 12 months to complete, the stability of a major institution can be reassuring during the many stages of construction and payment.
Pros:
- Full-service banking ecosystem.
- High level of institutional stability and security.
- Wide range of financial products available.
Cons:
- Stricter credit requirements compared to alternative lenders.
7. Tower Loan
Tower Loan provides a variety of specialized products, including home improvement and debt consolidation loans. They are a versatile option that can handle different financial needs, ranging from emergency cash to vacation planning or auto-secured loans. Their versatility makes them a «one-stop shop» for diverse financial situations.
They offer a structured approach to personal and installment loans. This makes them a useful option for homeowners who need to consolidate existing debt to free up cash for a specific home project, such as a new roof or flooring. For example, if you have three different high-interest credit card balances, consolidating them into one Tower Loan could lower your monthly outflow, freeing up the cash needed to pay your contractor.
Pros:
- Multiple loan types available for different needs.
- Option for debt consolidation to manage cash flow.
- Established presence with various service options.
Cons:
- Terms and availability vary significantly by location.
Comparing Loan Types: Personal vs. Equity-Based
Understanding the fundamental difference between loan types is essential for choosing the right vehicle. Most homeowners fall into one of two categories: those looking for personal installment loans or those looking for equity-based financing. Choosing the wrong one can lead to significantly higher costs or unnecessary risk to your home.
| Feature | Personal/Installment Loan | Home Equity Loan/HELOC |
|---|---|---|
| Collateral | Unsecured (No home as collateral) | Secured (Your home is collateral) |
| Interest Rates | Generally higher | Generally lower |
| Speed of Funding | Very Fast (Hours to days) | Slower (Weeks) |
| Approval Basis | Income and Credit Score | Home Value and Equity |
A personal loan (like those from NetCredit or Minute Loan Center) is «unsecured,» meaning if you fail to pay, the lender cannot immediately seize your house. This makes them safer for people with fluctuating incomes. A home equity loan, however, uses your house as collateral. While this usually results in a much lower interest rate, it means that your home is at risk if you cannot meet the monthly payments. For a small kitchen remodel, a personal loan is often the smarter, lower-risk move. For a $100,000 addition, the interest savings of a home equity product often outweigh the risk.
How to Navigate Your Financing Choices
Before you sign a single document, you must determine the scale of your project. A $5,000 flooring update requires a different financial tool than a $50,000 kitchen overhaul. Using a high-interest, short-term loan for a long-term structural project is a recipe for financial heartbreak. If you take a 24-month high-interest loan for a project that adds value to your home for 20 years, you are essentially paying a massive premium for the privilege of speed.
Always look for «no impact» inquiries. This allows you to shop around and see what you qualify for without damaging your credit score. Use the «soft pull» feature offered by many modern lenders to compare rates. Once you find a provider that fits, read the fine print regarding total interest paid over the life of the loan, not just the monthly payment. A «low monthly payment» can be an illusion if the term is stretched out over ten years, resulting in a massive total cost.
Avoid the trap of borrowing more than the project is worth. While it is tempting to take out a larger amount to cover «extra» upgrades like high-end marble countertops or a premium deck staining, you are essentially gambling with your home’s equity. Ensure that the value added to your home by the renovation is equal to or greater than the cost of the loan. Stay focused on your immediate needs and ensure your monthly budget can handle the new obligation without compromising your ability to pay for food, utilities, and emergency savings.