Top 4 Lenders for Uber Drivers Seeking Loans With Bad Credit in 2026
Last updated: 2026-11-08
Rideshare driving keeps many people afloat, but a sudden transmission failure or a surprise medical bill can wreck an entire week’s earnings. When your credit score is struggling, finding quick cash feels like driving through a heavy fog without headlights. It is a stressful, uphill climb for many gig workers navigating the modern economy.
Traditional financial tools often fail people who work as independent contractors. Most banking products were built for the steady, predictable paycheck of a 9-to-5 employee. They don’t always account for the reality of a driver who might make $1,200 during a holiday rush but only $600 during a slow, rainy week.
Picking a lender requires looking past the speed of the deposit. You have to weigh how fast you get the money against what it will eventually cost you. A $500 loan arriving in twenty minutes feels like a miracle when your alternator dies on a Friday night. However, if the interest is predatory, that $500 could end up costing you $1,500 over a few months.
This list examines how various lenders handle the irregular income streams that define the rideshare industry. We focused on finding options that prioritize your actual cash flow rather than just a FICO number.
- FastLendGo
- Giggle Finance
- OneMain Financial
- PaydayChampion
Evaluating Lenders for Independent Drivers
Qualifying for a loan despite a low credit score was our first priority. Traditional banks often turn their backs on gig workers because our income doesn’t look like a standard salary. They want to see two years of predictable paychecks from a single employer. They struggle to make sense of the «variable» nature of freelance work.
Speed of funding was our second major focus. If your car’s transmission dies, you cannot wait two weeks for a bank to approve your request. Every day that car sits in the shop is a day you aren’t earning, which creates a compounding loss of income. We looked for lenders that move as fast as a driver needs to.
We also checked the maximum loan amounts available. A small cash advance might fix a flat tire or a new sensor, but you might need more for a major engine overhaul. We looked at lenders that can cover both small hiccups and significant personal emergencies that might keep you off the road for a week.
| Lender Name | Max Loan Amount | Funding Speed | Credit Requirements |
|---|---|---|---|
| FastLendGo | $5,000+ | Quick access | Bad, Fair, & Good |
| Giggle Finance | $15,000 | Minutes | 1099/Self-Employed |
| OneMain Financial | $35,000 | As soon as 1 hour | Credit Check Required |
| PaydayChampion | $5,000+ | Minutes | No Credit Check Options |
Deep Dive: Understanding Loan Types for Gig Workers
Before you sign anything, you need to know what kind of financial tool you are picking up. Not all loans are created equal. Picking the wrong one can lead to a debt spiral where you are constantly borrowing just to pay off the interest from the previous loan.
Personal Loans vs. Cash Advances
A personal loan, like those from OneMain Financial, usually comes as a lump sum. You pay it back in fixed installments over several months or even years. This works well for major repairs, such as replacing an entire transmission or a full set of new tires and brakes.
A cash advance or short-term loan, like those from PaydayChampion, is meant for smaller, immediate needs. These act as quick fixes for urgent problems. While they are much faster to get, the interest rates are often significantly higher because the lender is taking a huge risk on a very short timeline.
Unsecured vs. Secured Loans
Most lenders on this list offer unsecured loans. This means you don’t have to put up your car as collateral. For rideshare drivers, this is a massive advantage. If you use a secured loan to fix your car and then struggle to make payments, the lender could repossess the very vehicle you need to earn money.
The catch is that unsecured loans are riskier for the lender. Because they have no collateral to fall back on, they charge higher interest rates. Understanding this trade-off is the key to staying in control of your money.
The Best Lenders for Rideshare Workers
1. FastLendGo
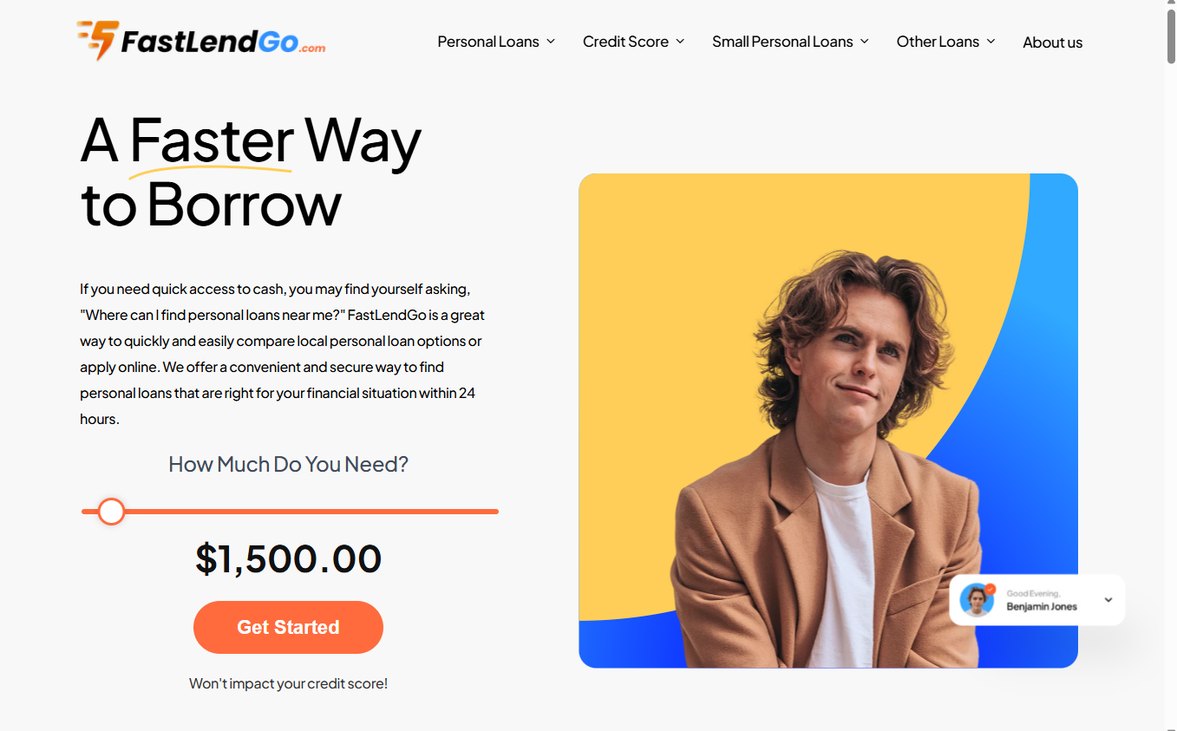
FastLendGo helps those who feel stuck because of their credit history. They work with a wide range of people, from those needing a $500 boost to those requiring much larger sums. It is a versatile choice for drivers facing sudden vehicle maintenance issues, like a new battery, brake pads, or an expensive sensor replacement. (fastlendgo.com)
The platform focuses on speed for various credit profiles. Whether you have fair credit or are struggling with bad credit, they offer tailored paths. This flexibility is vital for drivers who cannot afford to wait for traditional underwriting that might require physical paperwork or several days of verification.
Pros:
- Covers a wide range of loan amounts from $500 to over $5,000.
- Specifically caters to bad, fair, and good credit scores.
- Offers specialized financing for auto and motorcycle repairs.
Cons:
- Approval is subject to their specific internal criteria.
2. Giggle Finance
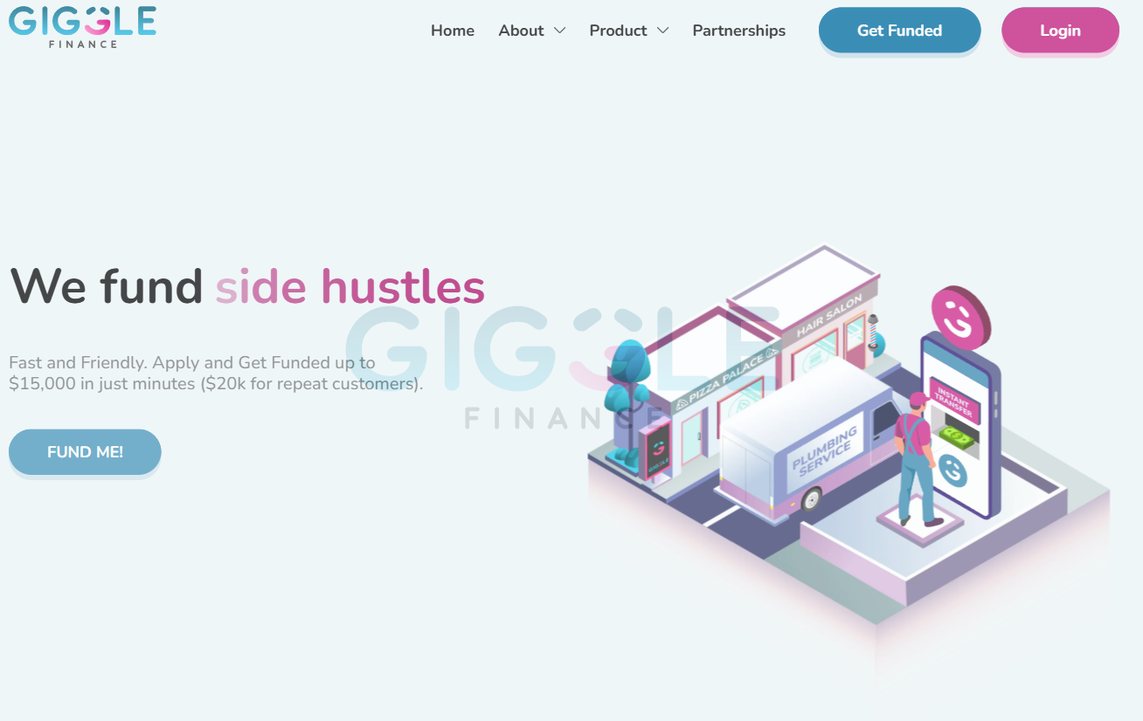
Giggle Finance is built specifically for the modern gig economy. They understand that a 1099 worker’s income looks different than a salaried employee’s. They don’t just stare at your credit score; they look at the reality of your digital earnings. For the Uber driver who lives for the hustle, this lender matches that fast-paced lifestyle.
They recognize that your income can spike during peak demand seasons or holiday rushes. They offer significant amounts, reaching up to $15,000 in just minutes. For repeat customers who show they can manage debt, that ceiling can climb even higher. It is an excellent choice for independent contractors who need to keep their wheels turning.
Pros:
- Extremely fast funding, often within minutes.
- High maximum limits for repeat customers.
- Tailored for 1099 and self-employed individuals.
Cons:
- High speed and high limits may come with higher interest costs.
3. OneMain Financial
OneMain Financial operates with a more traditional touch through their 1,300 physical branches. If you prefer looking a real person in the eye and explaining your situation rather than talking to an automated chatbot, this is a strong contender. They offer much larger loans intended for significant life changes or major capital investments.
With loans reaching up to $35,000, this is more of a long-term solution than a quick fix for a flat tire. They provide fixed monthly payments and flexible terms, making it easier to plan your budget. This is particularly helpful for drivers looking to upgrade to a more fuel-efficient model or a newer car with better safety ratings.
Pros:
- Large loan amounts up to $35,000.
- Access to physical branches for personal assistance.
- Fixed monthly payments for 24-60 months.
Cons:
- Requires a credit check to see your specific options.
4. PaydayChampion
PaydayChampion is the go-to for those facing a sudden emergency where even a few days is too long. They specialize in short-term, small-dollar loans designed to bridge the gap until your next platform payout. If your weekly earnings are caught in a processing delay and you need cash today for fuel, this is your high-speed option.
They offer specialized «no credit check» options, which can be a lifesaver when your score is in the basement due to past hardships. These loans are typically used for quick emergencies, helping you stay on the road when cash is tight and time is even tighter. They are the emergency toolkit of the lending world.
Pros:
- Offers short-term loans specifically for emergencies.
- Provides options for no credit check loans.
- Fast application process that takes only minutes.
Cons:
- Primarily focused on small, short-term amounts.
Strategic Borrowing: How to Protect Your Earnings
Taking out a loan should be a strategic move, not a desperate one. For a rideshare driver, your vehicle is your primary tool. If you use a loan to fix your car, you are investing in your ability to earn. If you use a loan for non-essential expenses, you are just eating into your future profits.
To manage this, calculate the «ROI» of the loan first. Before borrowing $1,000 for a repair, ask yourself how many extra hours of driving it will take to pay back that $1,000 plus interest. If the repair fixes a problem that was causing inefficiency, it pays for itself. If it’s a luxury upgrade, it’s a risk.
Always verify the APR. Never look at just the monthly payment. A $50 monthly payment might seem small, but if it lasts for 36 months and the interest is high, you’ve paid for the item three times over. Finally, try to build an emergency buffer. Once you get back on your feet, set aside even $20 a week. The goal is to ensure that the next time a tire goes flat, you aren’t looking for a lender.
Navigating Your Borrowing Choices
Before you sign anything, take a breath and look at the fine print. It is easy to get swept up in the excitement of «instant cash,» but the cost of that speed can be high. Always ask what the total cost of borrowing will be over the life of the loan, including all fees and potential late penalties.
Avoid the trap of taking out a loan just to pay off another loan. This creates a cycle that is incredibly hard to break. If you are an Uber driver, try to use these funds specifically for things that help you earn more, like a much-needed tire replacement or a mechanic visit that ensures you pass your next inspection.
Lastly, remember that your income can fluctuate. When you are choosing your repayment terms, don’t just look at your best week; look at your slowest. Building a safety net is much better than constantly chasing the next payday loan to keep your car running. Use these lenders as a tool to keep your business moving, not as a permanent crutch.